
by IMTFI Fellow and
International Board Member Noman Baig,
Habib University
 |
| Vendor at Jodia Bazaar, Karachi |
My interest in money stems from the incidents of 9/11 in the
United States. After the attacks in the US, all major governments and
international organizations passed stringent laws against informal money
transfer channels labeled as funding terrorism all over the world. In Pakistan,
the state curtailed the illegal funds transfer channel known as hawala by
arresting prominent currency dealers and passing the Anti-Hawala Act. A hawala
channel is a monetary network/practice that relies on centuries-old kinship
bonds for transferring value without moving physical cash from one place to
another. In place of these informal and embedded monetary channels, the state
opened up a market for multinational corporations such as Western Union and the
branchless banking sector to integrate hitherto unbanked people into the gambit
of modern finance under the national strategy called “financial inclusion.”
Despite the state’s coercive crackdown on moneychangers and
moneylenders in the country’s local bazaars, the lower-income labor class
continues to depend on such informal money channels to send and receive money.
These personalized networks allow them to feel secure that the money will reach
its destination safely. I conducted ethnographic research in Karachi’s
marketplace, Bolton Market, the largest wholesale bazaar of a variety of
commodities such as skin care, spices, fabric, steel, medicine, etc. While the
merchant community was under the direct surveillance of the state security
agencies, the laborers were freely moving their funds.
An archeology of funds transfer methods in Karachi’s Bolton Market
 |
| Bolton Market, Karachi |
During my research in these markets, I have discovered an
archeology of funds transfer methods. I call it an archeology because there are
layers of channels, often superimposed on each other, cross-cutting in many
cases, and undermining each other at various intervals. It can be called a
gradation of financial channels. For example, an informal hawala transfer made
through a local money changer passes through a kinship channel, but at some
point in a long chain the same transaction will intermingle with the formal
banking system. If the transaction raises a suspicious activity report, then
the Federal Investigation Agency (FIA) will examine it before the funds reach
their final destination.
 |
| Jodia Bazaar, Karachi |
Financial practices in Karachi’s marketplaces are a lattice work,
convoluted, and rhizomatic, making the location of the sources of a transaction
by the researcher a dizzying task. In just a single transaction the number of
actors involved can include a number of players, such as banks, moneychangers,
security agencies, merchants, etc. Sometimes transactions may include shrines,
mosques, and charity organizations by virtue of the mere fact that the gift
economy and commodity exchange are so tightly knit. Thus it becomes extremely
difficult to neatly categorize and differentiate one method of financial
transfer from another. In fact, it is also incorrect to use labels such as
“informal market,” which according to recent estimates is 75-90% larger than
the size of the “formal economy.” To be very clear, “informal” does not mean
that the market operates haphazardly, randomly, or irrationally, though it is
the kind of impression we generally get when we hear the word informal. In
fact, the informal market, if it can be neatly categorized as informal, does
not operate outside of the formal market. Both domains intermix with each other
at multiple locations.
Bhandari’s story – Considering migrant laborers in Karachi
The research I conducted engages with these multiple methods of funds transfer. One of the channels often used by laborers in Bolton Market involves a kin-based network of largely Pakhtun migrant workers in Karachi. One of the laborers who I became friends with is called Khan Zareen, also known as Bhandari in the market. Bhandari arrived in Karachi as a porter in the early 1980s. He started working in the city’s vegetable market (sabzi mandi) loading and unloading vegetables and fruit on his back. After the resettlement of the vegetable market to the outskirts of city, Bhandari decided to work in Bolton Market, where he started hauling heavy boxes to and from the warehouse.
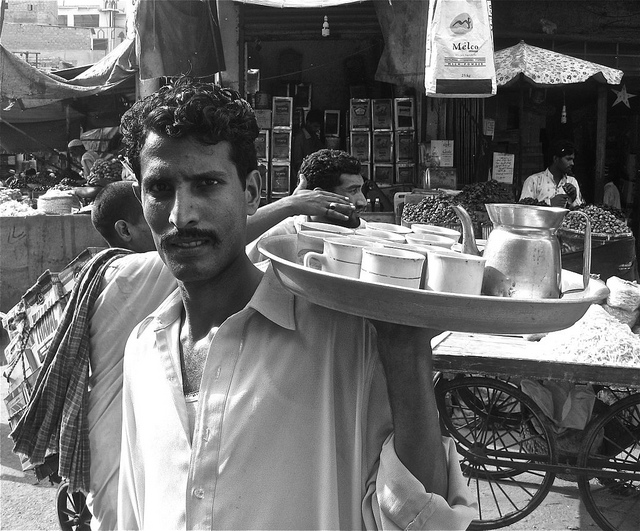 |
| Vendor at Jodia Bazaar, Karachi |
My encounter with Bhandari was sudden and unexpected. One day
while loading boxes on the cart to take it to bus station, he came to hear,
rather incorrectly, from a shopkeeper that I was a journalist writing a story
about the markets. Bhandari came rushing into the office and instructed me to
write about his suffering and condition. “Our houses have been destroyed in
Bajaur, and we never got any compensation from the government, while the
landowners (malik) are constructing new palatial houses,” he said. These
were the first words that Bhandari uttered to me bluntly. Initially I responded
to him by saying that I would tell his story, but that he would have to give me
more details. As the days passed, we became friends. Every time I would visit
Bolton Market, we would go to a chai dhabba (tea shop) for a cup of tea.
One day Bhandari showed me how he transfers money to his home in
Bajaur. He took me to another Pakhtun porter, who is known as Laal Zeb.
Bhandari handed over cash to Zeb and told him to deliver rice, ghee, wheat, and
sugar to his home. Laal Zeb took the cash and called his brother in Bajaur who
owns a food ration shop in the village. The next day, Zeb’s brother delivered
the goods at Bhandari’s house. There were no fees or charges for any part of
the entire transaction. Bhandari was able to buy food items for his family from
Karachi, while Zeb collected the cash for his brother’s shop in the village.
However, when Bhandari sends cash to the village via a moneylender/shopkeeper,
he has to pay Rs. 30 for every Rs. 1000 (which is still half of what branchless
banking services such as Easypaisa charge their customers). These are
personalized networks operated mainly by village communities who are spread
across rural and urban Pakistan. Porters such as Bhandari never go to the bank.
Several years ago, with the aid of the state officials, he managed to open a bank
account in a local bank branch in Bajaur to receive government compensation for
the reconstruction of his house, but after several years the bank account is
still waiting to receive funds from the government.
I asked him why doesn’t he use new services such as
Easypaisa—Pakistan’s largest branchless banking network—to send money. He
replied, “Easypaisa charges Rs. 60, while I pay Rs. 30 on every Rs. 1,000. Also
nobody in my home can get to an Easypaisa shop, which is outside of the
village.” In conservative tribal areas women are not allowed to go outside
alone. Bhandari has no male family members living in the village; his two sons
who are 22 and 14 also work in Karachi.
Although Easypaisa has become a phenomenal success among the
laboring classes in Karachi, and in Pakistan in general, Pakhtun laborers in
Bolton Market continue to use the old ways of sending and receiving money. They
use personalized channels such as Laal Zeb not only to transfer value, but also
to solidify affective bonds, social relationships, and ethnic ties. These
symbolic values play a determining role in maintaining community boundaries. In
an Easypaisa store, affective and ethnic relations are rendered unnecessary,
while the rationalized market ethos of efficiency, security, and instant
transaction takes precedence.
 |
| Vendor at Jodia Bazaar, Karachi |
Laborers such as Bhandari constitute the majority of Pakistan’s
working class who survive on less than $2/day. It is this sector of the
population that is seen as existing outside of the “real” economy, the domain
of modern, “formal,” rational, and bureaucratic finance propelled by identity
cards, paperwork, written records, and a survivalist ethos. The recent
financial sector development policies and practices are an effort to bring
laborers like Bhandari under the umbrella of the state and the corporate
economy through giving them easier access to savings, loans, and credits. One
of the ways proposed to implement this is to initiate a network of branchless
banking or retail agent banking. The state and corporations justify these
efforts as a favor to laborers, a remedy for alleviating their so-called
“miserable” conditions through the cure of financial inclusion.
Expanding the Discourse on Financial Inclusion
The agenda of financial inclusion to offer easy access to savings, loans, and credit to the masses, is fraught with inequalities and injustices. This is not to say that the laborers should cease using branchless banking. But to charge heavy fees for the services owned by a foreign corporation proves how terms of trade set during the colonial era continue to extract surplus value from the bones and flesh of the laborers. Most importantly, if international developmental organizations such as the World Bank are seriously interested in improving the financial conditions of the poor by bringing them inside of modern finance, then they should start by identifying the actual root causes of their exclusion. If they want to include these people, then the governments need to start a radical program of wealth redistribution through policies that allow its more even distribution. In other words, the poor masses all over the world are excluded because the wealthy few hold the wealth of 99 percent of the people. The majority will always stay excluded, and any financial inclusion program will fail miserably, unless a just economic system comes into place.
 |
| Laborers near Urdu Bazaar, Karachi |
The discourse of financial inclusion therefore demands a critical
scrutiny in light of the developmental ideology propagated in the postcolonial
world. With the beginning of modern colonialism in the mid-eighteenth century,
such efforts at integration and inclusion have resulted in an imbalanced power
structure and income inequality at a global scale. For instance, in British
India, colonial rule forced the integration of the vast land of the Indian
subcontinent, and its markets, its weavers and peasants, into the international
markets. The outcome was horrendous, and resulted in the siphoning of wealth and
resources from the colonies to the metropolis. Thus this is not the first time
that a serious effort at integrating the masses into the world economy has been
undertaken. The postcolonial world has been experiencing such programs of
integration for at least the last two hundred years, often with disastrous
consequences.
Read Noman Baig’s Final Report, “Branchless
Banking: Integrating Pakistan’s Poor in the Global Financial Circuit”
Stay tuned for a blogpost insights from "Financial
Inclusion of the Poor workshop" in Karachi, Pakistan.
Photos credits: Noman Baig


